
For insurance
A contents inventory in the shape insurers ask for
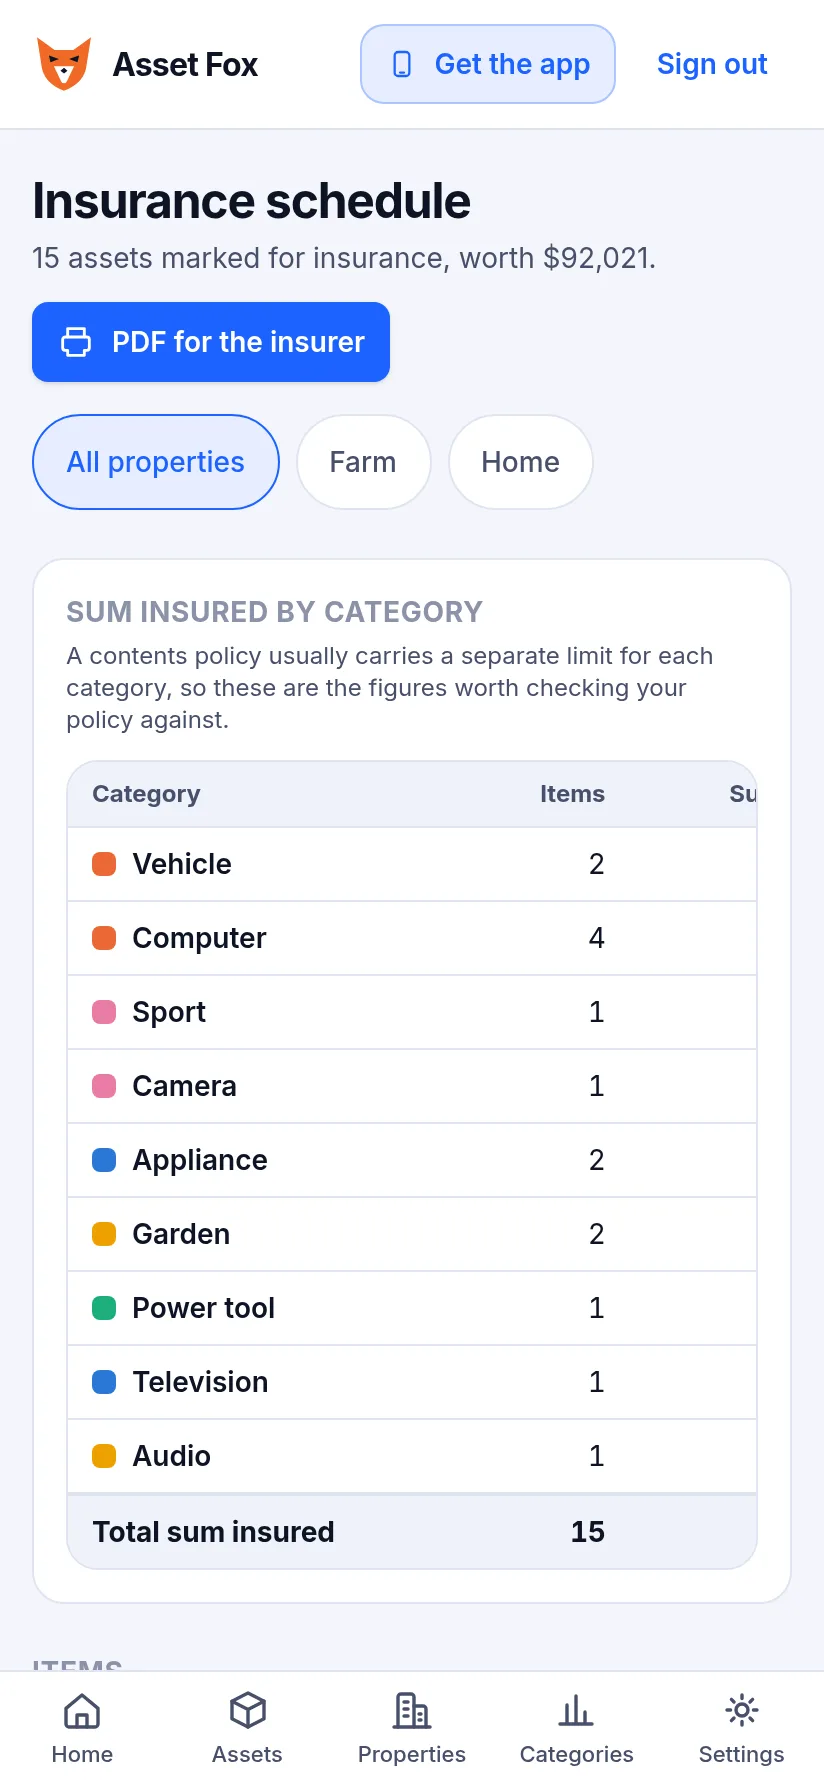
A single total is not the number that matters. Contents policies are written with a separate limit for each category of thing, and that is where people find out they were underinsured.
Why per-category totals matter
Knowing you own $47,000 of things tells you almost nothing. Knowing that $12,400 of it is computers, $6,000 is jewellery and $3,200 is power tools tells you whether each of those sits under the limit your policy sets for it. A category limit is the one that quietly caps a claim.
Asset Fox totals your insured items by category, largest first, because the largest is the one most likely to be short. The same figures print as a schedule you can send to a broker.
What the schedule contains
- Sum insured by category, with a grand total.
- Every item behind each figure - make, model, serial number, room and purchase date.
- A note saying which values came from a receipt and which are estimates, because an insurer treats those differently.
- Anything on the schedule with no value recorded, called out rather than quietly totalled as zero.
One schedule per address
A holiday house, a farm or an office usually has its own policy, and its insurer wants that address's contents and nobody else's. Keep each place as its own property and the schedule narrows to one of them with a tap - on screen and in the PDF.
Deciding what to insure
Anything over $500 is flagged automatically - you can change that figure, or answer any item yourself, and your answer sticks whatever the price turns out to be. The threshold is a starting point, not a rule.
After a loss
The value of an inventory is not in having it, it is in having it somewhere else. Print the schedule, keep a copy off the premises, and the conversation with a loss adjuster starts from a list with serial numbers on it rather than from memory.
Read next: building the inventory itself.